
Choosing a loan is an important financial decision. Whether you are planning to borrow for a home, vehicle, education, business, or personal requirement, different loan options can come with different interest rates, fees, repayment periods, and eligibility conditions.
Instead of selecting the first loan offer you find, it is useful to compare the available options carefully. A proper loan comparison helps you understand the overall cost of borrowing and identify a repayment plan that fits your budget.
Before applying, use this simple loan comparison checklist to review the important factors.
1. Compare the Interest Rates
The interest rate directly affects the cost of your loan. Even a small difference in the rate can change your monthly EMI and the total interest payable over the repayment period.
While comparing loans, check whether the interest rate is fixed or floating and understand the terms associated with it. Do not look at the advertised rate alone. Consider how the rate affects the total repayment amount.
Comparing interest rates across different loan offers can give you a better understanding of the long-term cost of borrowing.
2. Check the Loan Amount You Need
Before comparing loan products, determine how much money you actually need to borrow. Taking a higher loan amount than required can increase your EMI and overall interest cost.
Different lenders may have different minimum and maximum loan amounts. Your income, credit history, existing obligations, and repayment capacity can also influence the amount you may qualify for.
A suitable loan amount should address your financial requirement without putting unnecessary pressure on your monthly budget.
3. Compare EMI and Total Repayment
Monthly EMI is one of the most important factors when comparing loan options. However, a lower EMI does not necessarily mean a lower overall borrowing cost.
A longer repayment tenure can reduce the monthly EMI but may increase the total interest paid over the life of the loan. On the other hand, a shorter tenure may increase the EMI while reducing the overall interest cost.
A loan comparison calculator can help you compare different combinations of loan amount, interest rate, and tenure.
You can use it to estimate:
- Monthly EMI
- Total interest payable
- Total repayment amount
- Effect of changing the loan tenure
- Effect of different interest rates
These estimates can make it easier to understand which repayment structure fits your budget.
4. Check Your Loan Eligibility
Your loan eligibility is another important factor to consider before comparing loan offers. Lenders may assess your income, age, employment or business profile, credit history, existing liabilities, and repayment capacity.
Checking eligibility before applying can help you focus on loan options that are relevant to your financial profile.
An eligibility calculator can provide an initial estimate based on the information entered. However, eligibility requirements vary between lenders, and the final decision is subject to their assessment and applicable terms.
Understanding your eligibility can also help you determine whether the loan amount you want is realistic based on your financial circumstances.
5. Review Processing Fees and Other Charges
The interest rate is only one part of the cost of borrowing. Loan offers may also include processing fees and other applicable charges.
During your loan comparison, review the complete fee structure and check whether additional costs apply.
Depending on the loan product, you may need to look at:
- Processing fees
- Documentation charges
- Late payment charges
- Prepayment or foreclosure charges, where applicable
- Other service-related charges
Considering these costs can help you make a more accurate comparison between different loan offers.
6. Compare the Loan Tenure
Loan tenure determines how long you will make repayments. It can have a significant impact on both your EMI and total interest.
A longer tenure generally spreads repayment over more months, which can make the EMI more manageable. However, it may increase the total interest payable.
A shorter tenure can result in a higher monthly EMI but may reduce the total interest cost.
Use a loan comparison calculator to test different tenure options and see how they affect your estimated repayment.
7. Understand the Repayment Terms
Before choosing a loan, read the repayment conditions carefully. Check the EMI payment schedule, repayment frequency, and rules related to early repayment.
If you expect your income to change in the future or plan to make additional payments, understand the lender’s applicable terms for part-prepayment or early closure.
Knowing these conditions beforehand can help you avoid surprises during the repayment period.
8. Check the Lender’s Documentation Requirements
Different lenders may request different documents during the application process. These can include income proof, identity documents, address proof, bank statements, employment or business-related documents, and other supporting information.
Checking the documentation requirements before applying can help you prepare in advance and make the application process smoother.
You should also verify the terms and conditions provided by the lender before accepting a loan offer.
9. Consider Your Existing Financial Obligations
Your existing EMIs and financial commitments should be considered before taking another loan. A new EMI can affect your monthly cash flow and overall repayment capacity.
Before making a loan comparison, calculate how the proposed EMI would fit alongside your current obligations.
If the combined repayment burden becomes difficult to manage, consider whether you need a lower loan amount or a different repayment tenure.
10. Use a Loan Comparison Calculator Before Applying
When several loan options have different interest rates, loan amounts, and tenures, comparing them manually can be difficult.
A loan comparison calculator can make the process easier by allowing you to evaluate different repayment scenarios.
For example, you can compare:
Option A: Lower interest rate with a shorter tenure
Option B: Slightly higher interest rate with a longer tenure
The calculator can help you see how these differences may affect the estimated EMI, interest payable, and total repayment.
Remember that calculator results are estimates. Actual loan terms, interest rates, fees, and approval conditions depend on the lender and your individual application.
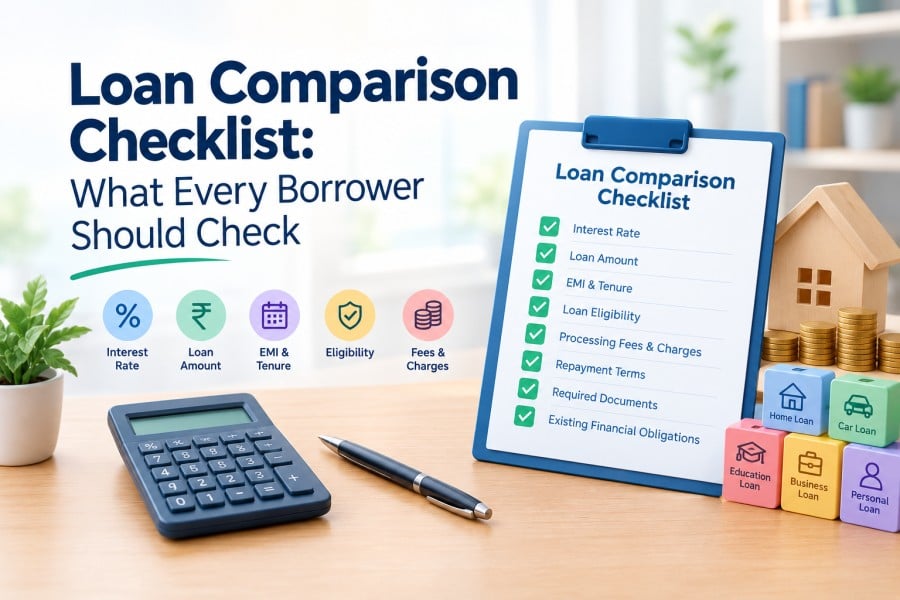
Loan Comparison Checklist Before Applying
Before submitting a loan application, make sure you have checked:
- Interest rate and applicable rate type
- Required loan amount
- Estimated EMI
- Total interest payable
- Total repayment amount
- Loan tenure
- Processing fees and other charges
- Loan eligibility requirements
- Repayment and prepayment conditions
- Required documents
- Existing financial obligations
Reviewing these points can help you compare loan options more systematically.
Final Thoughts
A loan should be evaluated based on its overall cost and suitability rather than one feature such as the interest rate. Effective loan comparison involves reviewing the interest rate, EMI, tenure, fees, repayment conditions, and loan eligibility.
Using a loan calculator can help you understand different repayment scenarios before applying. At the same time, checking your eligibility and considering your existing financial commitments can help you choose a loan structure that fits your financial situation.
Taking a little time to compare the important details can make the borrowing process more transparent and help you plan your repayments with greater confidence.