Growth rarely follows an unbroken trajectory, and expanding operations often requires more capital than initial projections anticipate. When an entrepreneurial venture scales, owners frequently tap several financing sources to keep pace with operational demands. Over time, combining short-term vendor credit, equipment financing, and emergency lines of credit can produce a complex web of obligations. Instead of supporting expansion, managing dispersed payments begins to drain daily focus and strain liquid reserves.
Recognizing when commercial obligations have become counterproductive is an essential initial step toward regaining control. Juggling varied due dates, differing interest structures, and competing lender demands creates unnecessary administrative friction. Rather than treating each payment as an isolated emergency, establishing a structured plan allows business owners to realign debt servicing with actual operational capacity.
Taking an Honest Inventory of All Commercial Liabilities
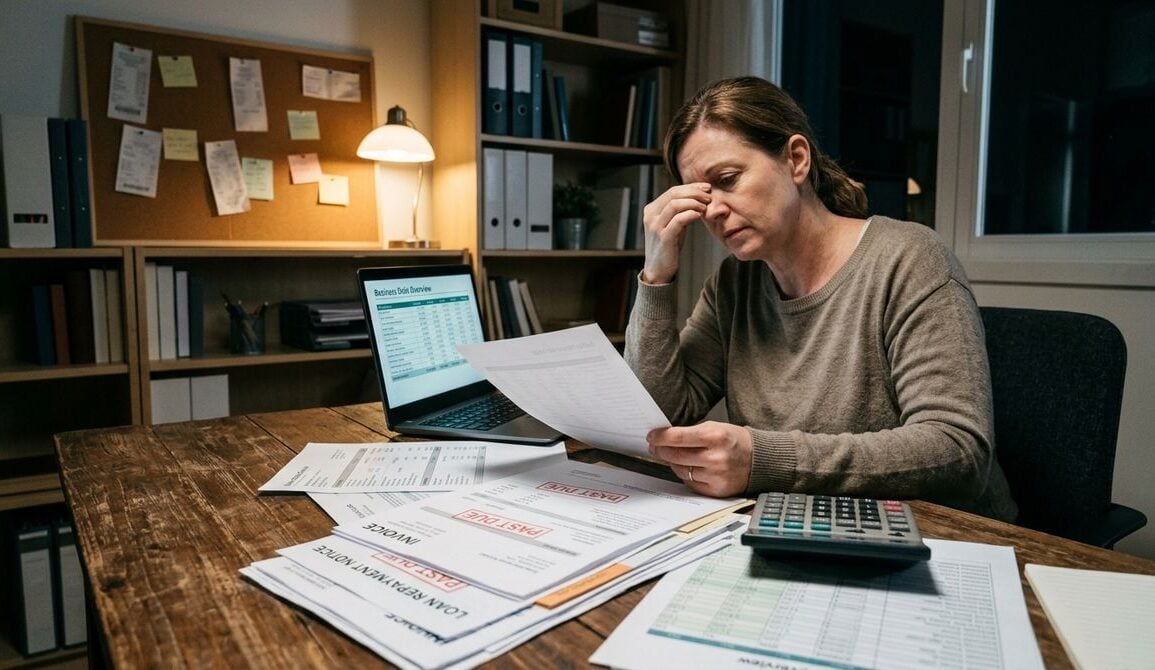
A clear recovery plan begins with complete visibility. When cash flow feels tight, business leaders sometimes avoid looking at the full liability picture in detail, focusing instead on whichever bill is due tomorrow. This piecemeal approach conceals the true cost of borrowing and makes proactive cash management nearly impossible. Laying out every financial obligation in a single ledger removes uncertainty and provides the baseline data required for sound decisions.
Documenting each commitment involves recording the creditor name, the remaining principal balance, the scheduled payment frequency, and any underlying covenants or pledged assets. Many small enterprises accumulate miscellaneous short-term obligations that carry unfavorable terms simply because they were easy to access during a pinch. When smaller obligations pile up across diverse vendors and lenders, reviewing resources such as rapid-debt-consolidation.com can clarify how streamlining several balances into a single predictable schedule might relieve immediate pressure on daily cash reserves.
Once the full liability roster is assembled, categorize each balance according to its urgency and security status. Secured debt tied to core operational equipment or commercial property requires different handling than unsecured vendor lines. Knowing exactly which liabilities threaten continuous operation enables you to make informed trade-offs rather than reactive compromises.
Prioritizing Cash Reserves and Opening Creditor Dialogues
Preserving core working capital must take precedence over satisfying non-critical obligations immediately. If paying a discretionary vendor leaves the company unable to cover payroll or critical utility bills, the business risks total operational disruption. Establishing an essential operating budget protects the functions that generate incoming revenue, supporting ongoing earning capacity while sorting through outstanding balances.
Once baseline operational needs are safeguarded, initiate direct communication with creditors before accounts lapse into formal default. Lenders and suppliers generally prefer structured settlements or adjusted payment schedules over prolonged silence. Approach these discussions with transparent explanations of current operations and a realistic timeline for regular remittances.
Before initiating contact with lenders, assemble a clear set of supporting materials to demonstrate your commitment to resolution:
- An updated summary of weekly operational revenues and essential overhead costs.
- A realistic proposal detailing adjusted payment amounts and proposed timeline extensions.
- A brief outline of corrective operational steps taken to curb unnecessary spending.
- An accurate record of historical payments showing your long-standing relationship.
Creditors frequently show willingness to waive late penalties, convert revolving balances into fixed term loans, or grant temporary grace periods when presented with structured proposals. Clear communication preserves critical commercial partnerships that would otherwise suffer permanent damage from unannounced payment delays.
Aligning Debt Relief With Broader Financial Advisory
Untangling multiple commercial loans requires more than arithmetic; it demands an honest evaluation of business fundamentals. High debt levels often mask deeper operational inefficiencies, such as poor pricing models, delayed invoicing cycles, or unprofitable service offerings. Treating the debt without diagnosing the underlying operational leak usually leads back to financial distress within a few billing cycles.
Bringing in specialized advisory support can provide an objective assessment of what your venture can realistically afford to service. Engaging with independent financial guidance platforms like extramoneyinfo.net offers practical insight into balancing debt relief with sustainable revenue generation, helping owners see beyond immediate fires toward long-term solvency.
External financial advisors help founders evaluate the cash conversion cycle, pointing out where receivables can be accelerated and how inventory holdings might be streamlined. By pairing liability restructuring with systemic improvements to working capital, a business works to support sustainable operations rather than recurring deficits.
Managing Team Morale and Culture Through Financial Strain
When cash becomes tight and management spends considerable energy restructuring balances, operational stress inevitably filters down to staff. Employees notice shifts in supplier availability, delays in minor purchases, or executive distraction. Unaddressed anxiety can damage productivity and cause valuable team members to look elsewhere, compounding business challenges at the worst possible moment.
Leadership during periods of restructuring demands consistent presence and grounded communication. While founders should avoid burdening frontline staff with complex financial specifics, acknowledging operational adjustments and sharing clear organizational goals builds shared purpose. Reassuring workers through stable leadership keeps the daily customer experience consistent and protects revenue generation.
Maintaining employee stamina and positive engagement is equally vital when finances tighten. Practical internal initiatives, such as creating a company health calendar, offer low-cost ways to sustain team cohesion, reduce workplace anxiety, and reinforce collective focus while leadership navigates complex operational transitions.
Establishing Long-Term Guardrails Against Overleverage
Successfully working through accumulated debt provides valuable operational lessons that must inform future financial governance. As cash flow normalizes, leadership teams must establish strict internal criteria governing when and how future debt is assumed. Debt should serve deliberate, revenue-generating investments rather than papering over chronic operating deficits.
One essential policy involves creating a dedicated operational reserve fund. Even small, disciplined allocations set aside during profitable periods create a vital buffer against future seasonal slumps or unexpected client defaults. Relying on internal reserves during lean months helps reduce the temptation to seek high-cost, short-term borrowing options that restart the cycle of distress.
In addition, routine financial reviews should become a standard leadership habit rather than an occasional chore. Monitoring key debt ratios, tracking payment turnaround times, and maintaining open relationships with primary lenders helps leadership catch and correct minor imbalances long before they threaten company operations.
Reorganizing commercial liabilities is fundamentally about regaining operational freedom and restoring clarity to business leadership. By cataloging obligations, communicating openly with lenders, addressing root operational causes, and maintaining a motivated workforce, entrepreneurs can steer their ventures away from financial distress toward resilient, self-sustaining growth.