Launching an independent retail enterprise often begins with identifying a compelling catalog and building a modern storefront. Yet for entrepreneurs operating in specialized or rapidly evolving niches, the most complex hurdles frequently emerge behind the scenes. Payment gateway freezes, unexpected rolling reserves, and sudden account closures can stall a promising brand without warning. Financial institutions evaluate applications through an underwriting framework designed to minimize institutional liability. When a category experiences shifting regulations, intense scrutiny, or unconventional buyer habits, traditional banking partners quickly implement defensive policies.
Entrepreneurs in these sectors cannot rely on standard playbooks alone. Sustaining healthy operations requires a cohesive strategy that balances underwriting expectations, banking redundancy, proactive consumer guidance, and cautious trend evaluation. By understanding how merchant processors assess risk and adapting internal workflows to meet stringent standards, business owners can maintain stable cash flow and protect long-term enterprise value.
Why Payment Processors Scrutinize Alternative Retail
Payment processors and acquiring banks operate on narrow margins while assuming substantial counterparty liability. When reviewing an application or monitoring an active merchant, underwriting teams analyze the legal durability of the product catalog, historical chargeback ratios across the sector, and the likelihood of consumer disputes. Product categories involving novel electronics, lifestyle consumables, or emerging financial tools are frequently classified as high risk because underwriters anticipate elevated dispute rates and changing regulations.
A primary operational concern for underwriters is chargeback frequency. When shoppers purchase technical merchandise without understanding how to operate it, frustration often leads to payment disputes rather than direct customer service requests. To an acquiring bank, rising disputes signal deficient fulfillment or misleading marketing. Even a modest uptick in chargeback filings can prompt a processor to hold funds in reserve or terminate processing agreements entirely, disrupting vital cash flow.
Mitigating this vulnerability requires business owners to approach payment processing as a core operational discipline. Maintaining clear documentation of shipping times, utilizing delivery confirmation tools, and presenting transparent transaction descriptors on customer billing statements substantially reduce inquiries. When underwriters observe that a company systematically resolves buyer confusion before it reaches a banking partner, they are far more inclined to provide consistent, stable service.
Reducing Returns Through Proactive Customer Guidance
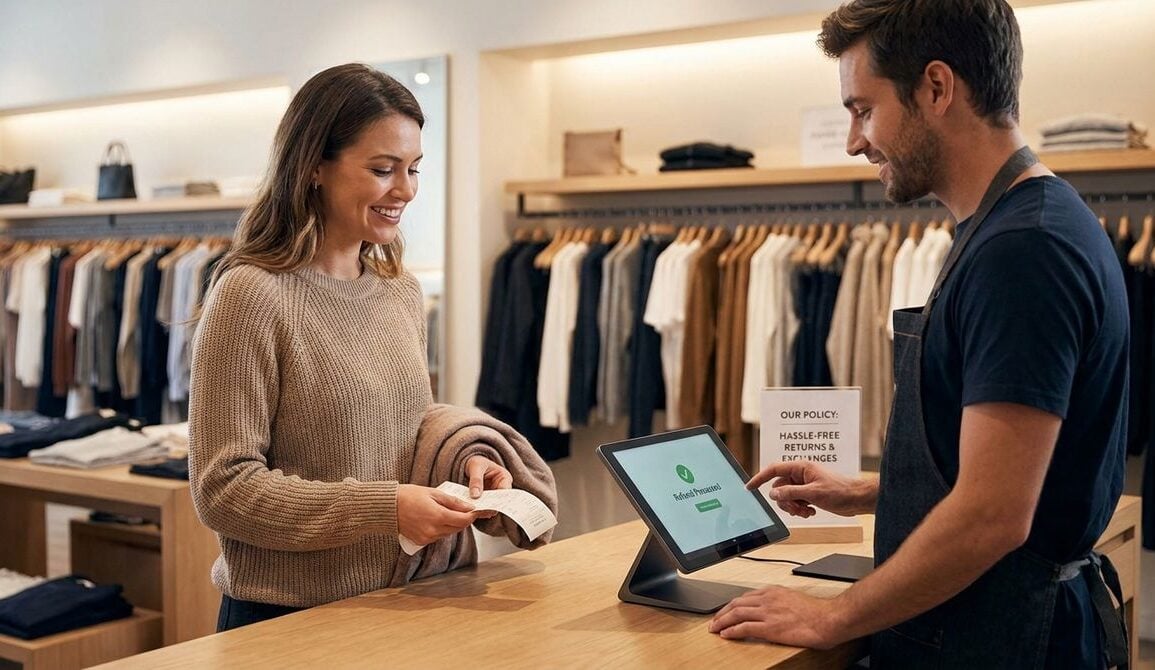
In specialized retail markets, technical complexity is often the primary driver of customer friction. When buyers receive advanced hardware or specialized accessories without clear setup instructions, minor difficulties quickly lead to product returns. Processing returns imposes administrative overhead, erodes gross margins, and signals operational weakness to payment partners. Retailers that invest in thorough buyer onboarding consistently experience fewer disputes and enjoy smoother fulfillment cycles.
Specialized educational hubs illustrate how dedicated guidance empowers consumers and reduces post-purchase dissatisfaction. For instance, platforms such as Geekay Vapes demonstrate how beginner tutorials, equipment maintenance guides, and candid product reviews help customers understand nuanced hardware before and after a purchase. When merchants integrate comparable instructional resources into their customer journeys—through setup manuals, unboxing walk-throughs, and troubleshooting pages—they help buyers resolve minor operating challenges independently.
Proactive guidance also demands complete clarity regarding product compatibility and limitations. Many customer disputes stem from unfulfilled expectations when an accessory fails to function with existing equipment. By publishing explicit compatibility charts and straightforward setup cautions, businesses prevent buyer remorse before an order ever leaves the distribution facility.
Exploring Alternative Settlement Rails and Digital Currencies
As conventional financial institutions tighten underwriting requirements for alternative retail niches, merchant operators increasingly seek payment redundancy. Depending entirely on a single credit card processor leaves a company vulnerable to sudden policy shifts or unannounced account holds. To build greater independence into their checkout infrastructure, forward-thinking entrepreneurs often evaluate digital currencies and blockchain settlement options that function outside conventional payment rails.
Adopting digital asset settlement provides valuable operational flexibility, but it also introduces technical and financial variables that require diligent monitoring. Price fluctuations, network transaction costs, and shifting regulatory attitudes demand steady oversight. To navigate this evolving landscape, business leaders frequently turn to dedicated market resources such as crypto 30x pro to follow digital asset developments, blockchain guides, and market trends that inform sound commercial decisions.
When incorporating digital currency payments, business owners must determine whether to retain digital assets on their balance sheet or utilize merchant tools that automatically convert payments into standard fiat currency. For companies with regular supplier obligations, automatic conversion eliminates price volatility while still offering consumers an alternative payment channel. Regardless of the chosen mechanism, maintaining accurate transaction records and defining clear refund protocols ensure clean accounting and steady operational continuity.
Separating Media Hype from Sustainable Product Demand
Operating in dynamic retail categories requires the discipline to distinguish between enduring consumer interest and temporary market hype. When a novel product category gains rapid public attention, enthusiastic commentary often heralds it as an indispensable commercial opportunity. In response, eager operators sometimes rush to commit substantial working capital, securing large inventory orders before confirming whether consumer demand represents a lasting shift or a fleeting phase.
Prudent founders counter this temptation by validating market enthusiasm against verified buyer feedback. Before allocating capital to speculative inventory lines or untried product categories, entrepreneurs benefit from reading trend stories with caution to separate sensational headlines from sustainable business fundamentals. This methodical mindset allows a company to introduce small product test batches, assess supplier reliability, and evaluate true margin performance without endangering baseline operations.
Systematic demand validation also protects merchant standing by preventing inventory liquidation crises. Sudden shifts in consumer sentiment can leave undisciplined retailers with excess stock that must be sold at steep discounts, depressing margins and disrupting cash flow. By monitoring reorder patterns and measuring organic customer inquiries over extended cycles, business leaders ensure that their capital remains allocated to dependable, profitable merchandise.
Essential Safeguards for High-Friction Commerce
Navigating high-scrutiny retail demands structural operational defenses rather than ad hoc reactions to processing interruptions. When entrepreneurs build operational resilience into daily procedures, external banking changes or supplier shifts become manageable events rather than catastrophic emergencies.
Retail founders operating in scrutinized categories should establish several foundational safeguards to protect ongoing business continuity:
- Maintain secondary merchant accounts across distinct banking providers to preserve uninterrupted checkout capabilities.
- Publish explicit return, refund, and shipping policies prominently throughout the checkout process.
- Conduct weekly transaction reviews to identify dispute patterns and address customer complaints promptly.
- Verify that all suppliers maintain verifiable compliance documentation for every catalog item.
Instituting these safeguards demonstrates operational maturity to underwriting partners and financial institutions. An enterprise that maintains organized dispute logs, accessible customer support channels, and reliable supplier relationships presents a significantly lower risk profile. Over time, this discipline earns favorable processing arrangements, reduced rolling reserves, and the stability needed to pursue sustainable growth.
Sustaining an independent retail business within high-scrutiny categories requires far more than compelling marketing and popular products. Long-term commercial success rests on steady underwriting management, transparent buyer communication, and disciplined trend assessment. By respecting the operational realities of merchant risk and establishing clear safeguards across every transaction channel, founders can steer their enterprises through uncertain market conditions with confidence.